




Restaurant Insurance in Fargo, North Dakota
If you're a Fargo restaurant owner searching for insurance that actually understands a record Red River crest the city held back with more than six million sandbags, a growing tech and healthcare economy anchored by a major Microsoft campus and two regional hospital systems, and a state where workers' comp can only be bought from one source, Insurance Kitchen builds coverage around that reality. We build Fargo restaurant coverage around your actual neighborhood and real local risk.
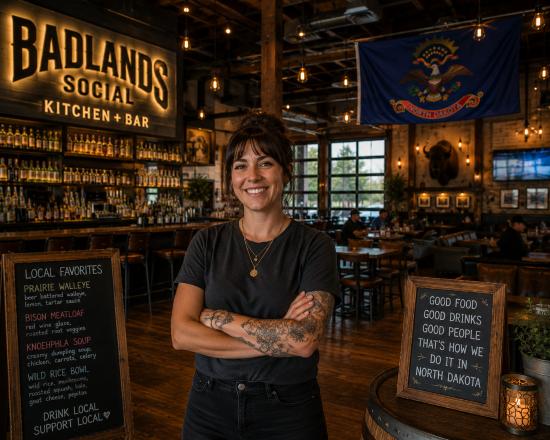
We know Fargo's restaurant scene block by block
Fargo's restaurant scene runs from a revitalized historic downtown that has held the Red River back more than once to a fast-growing tech and healthcare corridor pulling in new residents every year. Here's what we watch for across its neighborhoods.
Downtown / Broadway
Fargo's original commercial district sits closest to the Red River and carries the city's real annual flood-fight history along with a dense, older restaurant and bar scene where confirming actual replacement cost on aging kitchen wiring and plumbing is worth doing before renewing, not after a claim.
13th Avenue South / Osgood
Restaurants near Fargo's Microsoft campus, Sanford Medical Center, and Essentia Health's flagship hospital see steady weekday lunch and after-shift traffic from a genuinely different customer base than the tourist-driven cities this project has built in other states, which shapes both liability exposure and revenue patterns.
Core coverage lines every Fargo restaurant should evaluate
Restaurant insurance in Fargo is a tailored bundle built around North Dakota law, local licensing, and your lease. Here's what actually protects Fargo food service businesses.
General Liability Insurance
Protects against third-party bodily injury and property damage claims. Responds when guests slip, suffer foodborne illness, or get injured during delivery. Most landlords require $1M/$2M before lease signing.
Commercial Property Insurance
Covers your kitchen equipment, refrigeration and HVAC, tenant improvements, inventory, and business personal property against fire, equipment breakdown, and theft.
Business Owner's Policy (BOP)
Bundles general liability, commercial property, and business interruption into one package. Works best for single-unit restaurants with annual revenue under $3 million.
Liquor Liability Insurance
North Dakota has real civil dram shop liability: N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee or social host who knowingly furnished alcohol to that person, a minor, or an incompetent individual, with a six-year statute of limitations. Knowingly serving a prohibited person is also a class A misdemeanor under section 5-01-09. Standalone liquor liability coverage is essential, not optional, for any North Dakota establishment that serves alcohol.
Workers' Compensation Insurance
North Dakota is a monopolistic workers' comp state: coverage is mandatory from your first employee, full time, part time, seasonal, or occasional, but it can only be purchased through the state fund, Workforce Safety & Insurance (WSI); no private carrier is allowed to sell it here. Operating uninsured exposes an employer to the full cost of any claim plus a real penalty of up to $10,000, and it is illegal to deduct any part of the premium from an employee's wages.
Business Interruption Insurance
Replaces lost income and covers ongoing expenses when covered events force shutdowns or reduced capacity. Limits should reflect 3 to 6 months of net income plus fixed expenses.
What restaurant insurance typically costs in Fargo
A rough range based on real North Dakota market data. Not a quote, just a starting point before you talk to an agent about your specific Fargo location.
| Coverage | Typical Range | Why |
|---|---|---|
| General Liability Insurance | $540-$1,500/yr | North Dakota rates generally track about 15% below the national average, though Fargo's status as the state's largest and densest metro pushes local premiums above the statewide rural baseline. |
| Liquor Liability Insurance | $480-$1,020/yr | North Dakota has real civil dram shop liability under N.D. Cent. Code section 5-01-06.1, with a six-year statute of limitations and a liability standard that also reaches social hosts, not just licensees, making this coverage a genuine necessity rather than a formality. |
| Commercial Property w/ Flood & Freeze Review | $960-$1,320/yr | Fargo's 2009 flood fight and its regular sub-zero winter stretches are two separate, documented reasons to confirm your specific address's flood-zone status and your policy's frozen-pipe and roof-collapse coverage before the next spring thaw or cold snap, not after. |
| Workers' Compensation (WSI, mandatory from your first hire) | $648-$2,100/yr | North Dakota workers' comp can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier, and it's mandatory the moment a Fargo restaurant hires anyone, even a part-time host. Skipping it risks the full cost of any claim plus a real penalty of up to $10,000. |
| Business Owner's Policy (BOP), Bundled | $1,620-$1,800/yr | Bundles general liability and commercial property at a discounted rate, the standard starting point for most single-unit Fargo cafes and fast-casual concepts. |
| Full-Service, High-Volume, Bundled | $7,200-$12,000/yr | Downtown and Broadway full-bar restaurants with 15+ staff should budget toward this range; a comprehensive Fargo package typically runs $1,800-$7,200/yr overall depending on alcohol service and payroll, per WSI's own premium filing. |
Why Fargo's flood history and North Dakota's single-source workers' comp system change what your policy needs to do
Fargo restaurant coverage has to account for a real, documented flood benchmark the city has now defended against more than once, layered against a state workers' comp system that runs nothing like the private-carrier market this project has seen in every other state so far.
The 2009 flood fight is Fargo's own documented benchmark for spring risk
Beginning in March 2009, the Red River rose for weeks and crested at a record 40.84 feet in Fargo on March 28. Volunteers placed more than six million sandbags and built roughly 6.3 miles of emergency levee, and the city held the water back without a catastrophic breach, unlike Grand Forks' experience in 1997. That successful defense is exactly why Fargo restaurant owners should confirm their commercial property policy's flood coverage and deductible now, while the risk is a planning exercise rather than an active emergency.
North Dakota workers' comp only has one seller, and that changes how you shop for it
Under state law, every North Dakota employer must carry workers' comp from the first employee, but the policy itself can only come from Workforce Safety & Insurance, the state fund; no private insurer is permitted to write it here. That means a Fargo restaurant's WSI premium isn't something Insurance Kitchen can shop across carriers the way we do with liability or property, but we still help owners get classified correctly and understand what WSI actually requires before their first hire starts.
A new Fargo restaurant hires its first part-time dishwasher before setting up a WSI policy, and the employee is injured during a busy shift.
A closer look at how Fargo's documented risk factors actually play out.
A new Fargo restaurant hires its first part-time dishwasher before setting up a WSI policy, and the employee is injured during a busy shift.
- The setup: A first-time Fargo owner assumes workers' comp is something to arrange once the business has a few employees, not one.
- The direct impact: North Dakota law requires WSI coverage from day one of any employee's first shift, full time or not, and the restaurant is now operating uninsured with an active claim on the table.
- The coverage question: Confirm your WSI policy is active before your first hire's first shift, not after, since North Dakota gives no grace period tied to headcount or hours.
- The fix: Setting up WSI coverage the same week you extend a job offer, not the week the new hire starts, is what actually keeps a Fargo restaurant inside the law and protected.
This is exactly why Fargo-specific coverage matters. A generic answer of "get workers' comp once you're established" misses that North Dakota's mandate has no headcount threshold at all.
Frequently asked questions
How much does restaurant insurance cost in Fargo?
A comprehensive restaurant insurance package in Fargo typically runs $1,800 to $7,200 per year for most single-unit operators, with full-bar, high-volume restaurants running $7,200 to $12,000 or more. General liability runs roughly $540 to $1,500 per year; a bundled BOP runs $1,620 to $1,800 per year; liquor liability runs $480 to $1,020 per year. North Dakota's rates generally track about 15% below the national average, though Fargo's density as the state's largest city pushes local premiums above the statewide rural average.
Is workers' compensation required for a small Fargo restaurant?
Yes, from the moment you hire your first employee, full time, part time, seasonal, or occasional. North Dakota is a monopolistic workers' comp state, meaning coverage can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier. Operating without it exposes a Fargo restaurant to the full cost of any injury claim plus a real penalty of up to $10,000, and it's illegal for an employer to deduct any part of the premium from a worker's paycheck.
Can a Fargo restaurant be sued for over-serving a customer?
Yes, and the exposure is broader than in many states. N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee, or even a social host, who knowingly served that person, a minor, or an incompetent individual, with a six-year window to file. Knowingly serving a prohibited person is separately a class A misdemeanor that can put a liquor license at risk. Standalone liquor liability coverage is essential for any Fargo restaurant or bar serving alcohol.
Does the 2009 flood still matter for restaurant insurance in Fargo today?
Yes, as the city's own documented benchmark for spring flood risk. The Red River crested at a record 40.84 feet in Fargo on March 28, 2009, and the city held it back with more than six million sandbags rather than experiencing a breach. Fargo restaurant owners, especially downtown and along the riverfront, should confirm their commercial property policy's flood coverage and deductible reflect that real local risk rather than assuming a generic statewide rate applies.
What kind of insurance does a Fargo restaurant actually need?
The core package is general liability, commercial property, and liquor liability if you serve alcohol, often bundled into a Business Owner's Policy for savings. Workers' compensation is legally required from your very first employee and has to be purchased directly through North Dakota's state fund, WSI, rather than shopped across private carriers the way the rest of your coverage can be.
Get Fargo restaurant coverage built around your actual neighborhood and real local risk.
Tell us your concept and your Fargo neighborhood. We'll put together the coverage that actually applies.
Get Your Free Quote →