



Restaurant Insurance in Winston-Salem, North Carolina
Forsyth County's Helene declaration carries an incident period running from 25 September to 18 December 2024, which is the detail worth sitting with: the event did not end for nearly three months. On the liability side there is a gap most operators here have not been told about. North Carolina's civil dram shop claim reaches only underage drivers, but serving a visibly intoxicated adult is still unlawful under the permit statute, and that is where the exposure actually lives.
We know Winston-Salem's restaurant districts block by block
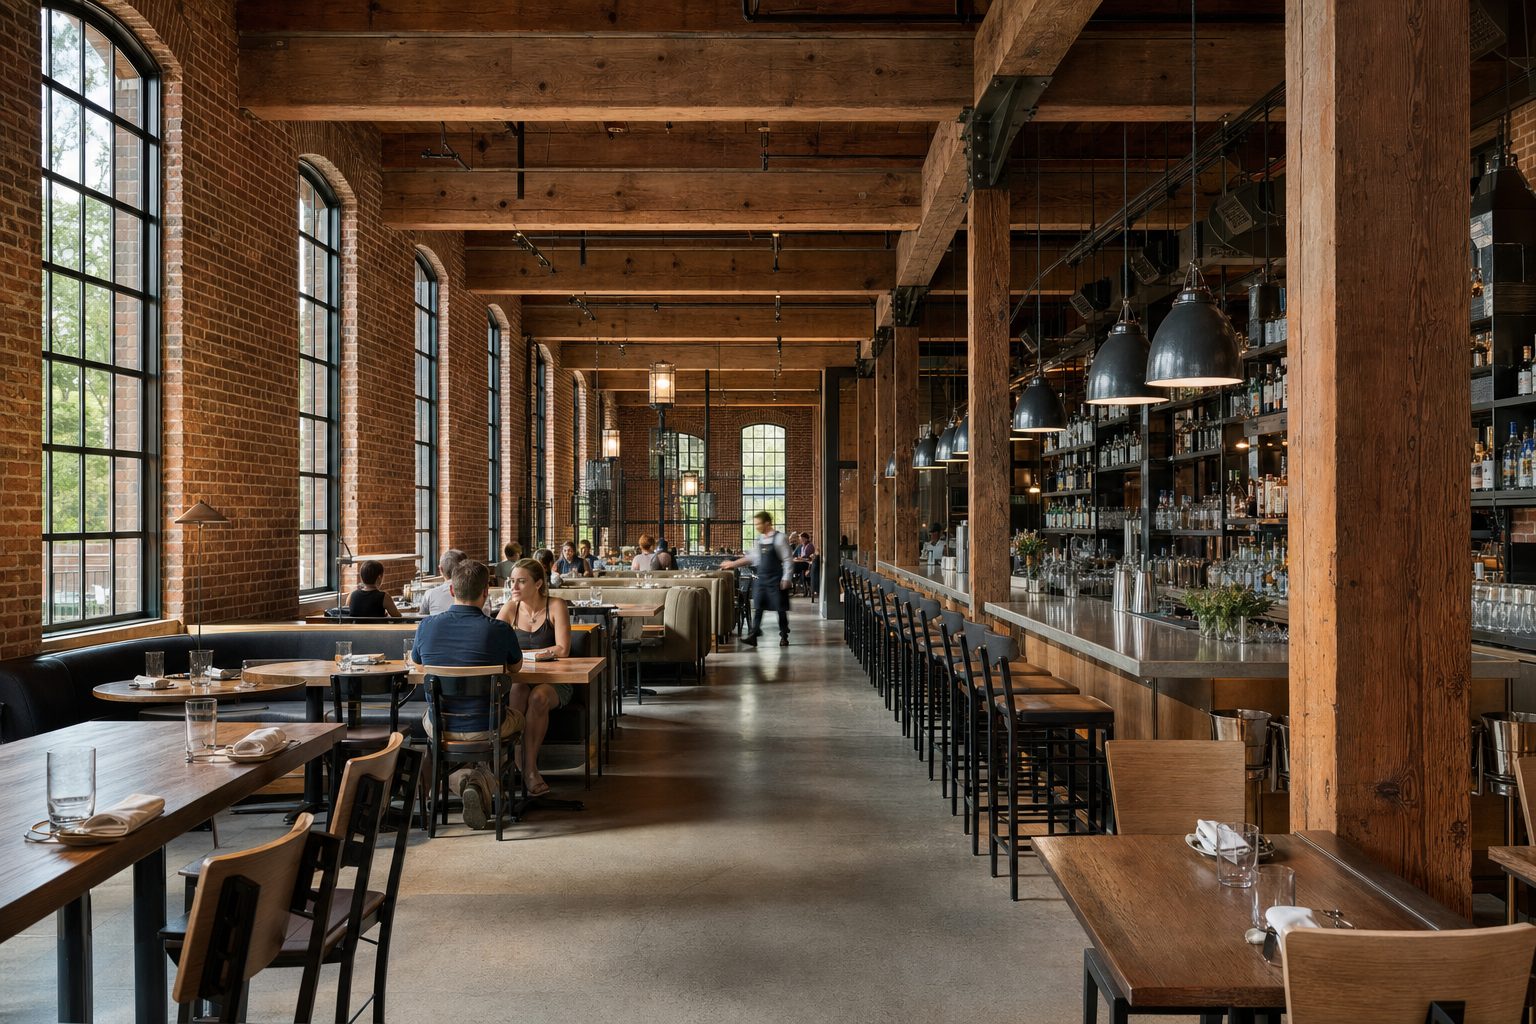
Winston-Salem runs an arts-and-innovation downtown alongside long-established neighborhoods, with a building stock that remembers the tobacco industry.
Citywide, after a declared event
A county whose most recent declaration ran for nearly three months. Recovery timelines here are measured against supply chains and contractor availability, not against the weather.
The Innovation Quarter and Trade Street
Bars and restaurants where the evening carries the revenue. The civil claim is narrow in North Carolina; the permit exposure is not.
The old tobacco buildings
Large-floorplate conversions with modern kitchens inside heavy masonry. Replacement cost on these diverges sharply from a square-foot estimate.
Kitchens citywide
Statutory requirements and Commission orders that carry a direct financial consequence if ignored, over and above the injury itself.
West End and Ardmore
Smaller rooms with thin margins, where an extended closure is the thing most likely to end the business.
Core coverage lines every Winston-Salem restaurant should evaluate
A Winston-Salem policy has to be sized for a recovery measured in months, and for an alcohol exposure that the civil statute does not describe.
General Liability Insurance
Trade Street evening volume concentrates a lot of people into a few hours. This line meets guest injury and third-party property damage arising out of the premises and your operations.
Commercial Property Insurance
An incident period of nearly three months says more about recovery than about wind speed. Price property against a realistic rebuild in a market where every contractor is busy at once.
Business Owner's Policy (BOP)
One West End dining room generally fits a business owner's policy, which places property and general liability together for less than the two placed apart.
Liquor Liability Insurance
The civil claim and the permit rule do not line up. North Carolina's statutory dram shop action is confined to negligent sales to underage drivers, but it remains unlawful for a permittee or employee to knowingly sell or give alcoholic beverages to any person who is intoxicated, which is a permit and criminal exposure sitting exactly where owners assume there is none.
Workers' Compensation Insurance
Ignoring a statutory duty costs an extra tenth. Where an injury or death is caused by the willful failure of the employer to comply with any statutory requirement or any lawful order of the Commission, compensation is increased by ten percent.
Business Interruption Insurance
Three months of declared incident is three months of disrupted trading. Business interruption needs an indemnity period matched to the real recovery rather than to the repair invoice.
What restaurant insurance typically costs in Winston-Salem
Winston-Salem prices close to the Piedmont norm, with the recovery timeline mattering more than the premium. Treat the figures below as a planning band.
| Coverage Type | Typical Annual Range | Why It Varies in Winston-Salem |
|---|---|---|
| General Liability Insurance | $500-$1,750/yr | Evening volume and the density of the trade district drive this. |
| Commercial Property (masonry conversion) | $1,100-$4,000/yr | Heavy converted stock costs more to reinstate than a square-foot estimate suggests, especially when contractors are stretched. |
| Liquor Liability Insurance | $850-$2,900/yr | Alcohol share of revenue is the driver, and the permit exposure runs wider than the civil claim. |
| Workers' Compensation | Payroll-class rated | Mandatory at three or more employees, with a ten percent uplift on compensation where the employer willfully ignored a statutory requirement or a Commission order. |
| Business Interruption, extended period | Rated by exposure | Worth sizing against a months-long recovery rather than the construction schedule. |
| Full Program, No Alcohol | $1,100-$4,900/yr | A baseline for a full-service room before alcohol is added. |
| Full Program w/ Alcohol | $4,000-$9,500/yr | The upper end reflects alcohol-led evening revenue in converted stock. |
Why serving an intoxicated adult is still a problem in a state with a narrow dram shop law
North Carolina has an unusually confined civil dram shop claim, and that fact gets repeated until it sounds like permission. It is not. The civil route is narrow; the permit route is not, and a permit action can close a restaurant faster than a lawsuit ever would.
The permit rule the civil statute does not cover
Forsyth County was designated under DR-4827, Tropical Storm Helene, with a declared incident period running 25 September to 18 December 2024. Separately, G.S. 18B-305(a) makes it unlawful for a permittee, an employee of a permittee, or an ABC store employee to knowingly sell or give alcoholic beverages to any person who is intoxicated. The same section preserves a seller's discretion to refuse anyone, while prohibiting refusal based solely on race, religion, color, national origin, sex or disability.
The ten percent uplift
G.S. 97-12 provides that where an injury or death is caused by the willful failure of the employer to comply with any statutory requirement or any lawful order of the Commission, compensation shall be increased ten percent. The section places the burden of proof on whoever claims an exemption or forfeiture under it.
How an indemnity period sized to the repair runs out before the recovery does
The construction schedule and the trading recovery are different lengths, and in a county whose declared incident ran twelve weeks, the gap between them is where a business fails.
Your Innovation Quarter room is repaired in eight weeks and quiet for five months
- The setting: The declared Forsyth County incident period for Helene ran from 25 September to 18 December 2024. Your building is repairable, but the district around it takes far longer to come back.
- The gap: An indemnity period written to cover the works expires when the works finish. Revenue does not return on that schedule, particularly where neighboring premises, staff housing and customer habits all have to recover together.
- The fix: The indemnity period is set against observed recovery rather than contract duration, extended period of indemnity is priced deliberately, and dependency on neighboring trade is discussed rather than assumed away.
- The result: Cover that keeps paying through the quiet months after the building is technically finished.
The building being ready and the business being back are not the same date, and only one of them is in the builder's contract.
Frequently asked questions
How much does restaurant insurance cost in Winston-Salem, North Carolina?
A full-service Winston-Salem restaurant with alcohol commonly runs $4,000 to $9,500 a year across property, general liability, liquor liability and workers' compensation. Converted masonry buildings and alcohol-led evening revenue are the two factors that move it most.
Can I be penalised for serving an intoxicated adult in North Carolina?
Yes, under the permit statute even though the civil claim is narrow. G.S. 18B-305(a) makes it unlawful for a permittee or employee to knowingly sell or give alcoholic beverages to any person who is intoxicated. The statutory civil dram shop action is confined to negligent sales to underage drivers, so the two do not cover the same ground.
What happens if an employer ignores a safety requirement in North Carolina?
Compensation goes up. G.S. 97-12 provides that where injury or death is caused by the willful failure of the employer to comply with any statutory requirement or any lawful order of the Industrial Commission, compensation shall be increased ten percent, with the burden of proof on whoever claims the exemption or forfeiture.
How long should my business interruption indemnity period be?
Longer than the construction program. The declared Forsyth County incident period for Helene ran from 25 September to 18 December 2024, and trading recovery in a damaged district routinely lags the repair by months. An extended period of indemnity is the provision that addresses the difference.
Does my property policy cover a converted industrial building properly?
Only if the sum insured reflects what reinstating it would actually cost. Heavy masonry conversions with modern kitchens inside them are the classic underinsurance case, because a generic square-foot figure misses both the structure and the fit-out.
Is liquor liability required in North Carolina?
It is not mandated by statute the way it is in some states, but landlords and lenders routinely require it, and the permit exposure under G.S. 18B-305 exists regardless of whether a civil claim would succeed.
Get Winston-Salem coverage sized to the recovery, not the repair.
Tell us what the building is, how late you pour and how much of your trade depends on the street around you. We'll build a program with an indemnity period that survives a slow district.
Get Your Free Quote →