




Restaurant Insurance in West Fargo, North Dakota
If you're a West Fargo restaurant owner searching for insurance that actually understands a city that grew nearly 50% in a single decade, a retail corridor built almost entirely on new construction rather than legacy downtown buildings, and a state where workers' comp can only be bought from one source, Insurance Kitchen builds coverage around that reality. We build West Fargo restaurant coverage around your actual neighborhood and real local risk.
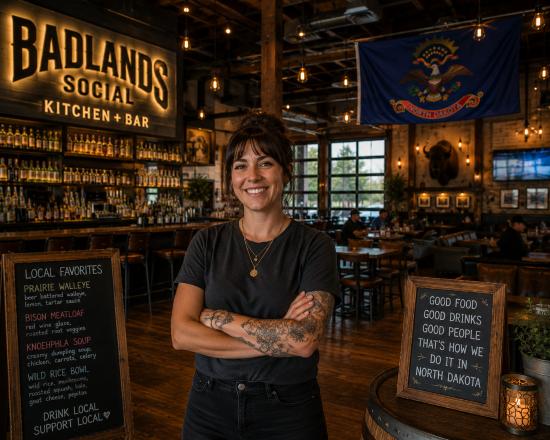
We know West Fargo's restaurant scene block by block
West Fargo's restaurant scene runs almost entirely through new construction rather than a historic downtown, concentrated along a retail corridor that's expanded as fast as the city's population. Here's what we watch for across its neighborhoods.
Sheyenne Street / 13th Avenue West
West Fargo's primary restaurant and retail corridor has been built almost entirely in new construction over the past 15 years, which means fewer old-building surprises but a different set of questions to ask before opening: confirming your builder's risk coverage during buildout, and checking that your business personal property limits keep pace with new equipment, since new leases and new kitchens change those numbers fast.
Main Avenue / Downtown West Fargo
West Fargo's older, smaller original downtown carries a steadier, more established customer base than the newer retail corridor, and restaurants here benefit from being close enough to Fargo proper to draw cross-city traffic without competing directly on the busiest new-construction blocks.
Core coverage lines every West Fargo restaurant should evaluate
Restaurant insurance in West Fargo is a tailored bundle built around North Dakota law, local licensing, and your lease. Here's what actually protects West Fargo food service businesses.
General Liability Insurance
Protects against third-party bodily injury and property damage claims. Responds when guests slip, suffer foodborne illness, or get injured during delivery. Most landlords require $1M/$2M before lease signing.
Commercial Property Insurance
Covers your kitchen equipment, refrigeration and HVAC, tenant improvements, inventory, and business personal property against fire, equipment breakdown, and theft.
Business Owner's Policy (BOP)
Bundles general liability, commercial property, and business interruption into one package. Works best for single-unit restaurants with annual revenue under $3 million.
Liquor Liability Insurance
North Dakota has real civil dram shop liability: N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee or social host who knowingly furnished alcohol to that person, a minor, or an incompetent individual, with a six-year statute of limitations. Knowingly serving a prohibited person is also a class A misdemeanor under section 5-01-09. Standalone liquor liability coverage is essential, not optional, for any North Dakota establishment that serves alcohol.
Workers' Compensation Insurance
North Dakota is a monopolistic workers' comp state: coverage is mandatory from your first employee, full time, part time, seasonal, or occasional, but it can only be purchased through the state fund, Workforce Safety & Insurance (WSI); no private carrier is allowed to sell it here. Operating uninsured exposes an employer to the full cost of any claim plus a real penalty of up to $10,000, and it is illegal to deduct any part of the premium from an employee's wages.
Business Interruption Insurance
Replaces lost income and covers ongoing expenses when covered events force shutdowns or reduced capacity. Limits should reflect 3 to 6 months of net income plus fixed expenses.
What restaurant insurance typically costs in West Fargo
A rough range based on real North Dakota market data. Not a quote, just a starting point before you talk to an agent about your specific West Fargo location.
| Coverage | Typical Range | Why |
|---|---|---|
| General Liability Insurance | $504-$1,440/yr | North Dakota rates generally track about 15% below the national average, and West Fargo's rapid growth keeps demand for coverage rising faster than in most of the state's smaller cities. |
| Liquor Liability Insurance | $456-$960/yr | North Dakota has real civil dram shop liability under N.D. Cent. Code section 5-01-06.1, with a six-year statute of limitations that reaches social hosts as well as licensees, making this coverage a real requirement, not a formality, for any new West Fargo restaurant opening with a full bar. |
| Builder's Risk & Commercial Property Review | $900-$1,380/yr | West Fargo's growth has been built almost entirely on new construction, which makes confirming builder's risk coverage during any buildout or remodel, and updated business personal property limits once you open, a real and recurring conversation rather than a one-time setup. |
| Workers' Compensation (WSI, mandatory from your first hire) | $588-$1,920/yr | North Dakota workers' comp can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier, and it's mandatory from a West Fargo restaurant's very first employee. Operating uninsured risks the full cost of any claim plus a real penalty of up to $10,000. |
| Business Owner's Policy (BOP), Bundled | $1,560-$1,800/yr | Bundles general liability and commercial property at a discounted rate, the standard starting point for most single-unit West Fargo restaurants opening in new Sheyenne Street retail space. |
| Full-Service, High-Volume, Bundled | $6,600-$11,400/yr | Sheyenne Street full-bar restaurants with 15+ staff should budget toward this range; a comprehensive West Fargo package typically runs $1,800-$6,600/yr overall depending on alcohol service and payroll. |
Why West Fargo's rapid growth and North Dakota's single-source workers' comp system change what your policy needs to do
West Fargo restaurant coverage has to account for a physical footprint that's still being built out, unlike most cities this project has covered, layered against a state workers' comp system that only has one approved seller no matter how new the restaurant is.
West Fargo's growth rate is North Dakota's own documented benchmark for new-construction risk
The U.S. Census Bureau recorded West Fargo's population growing from roughly 25,830 in 2010 to 38,626 at the 2020 census, a 49.82% increase in a single decade, with an estimated 41,027 residents by 2024, making it the fastest-growing and 5th-most populous city in North Dakota. That growth has been absorbed almost entirely through new construction along the Sheyenne Street corridor rather than a historic downtown, which is exactly why confirming builder's risk coverage during any buildout, and updated business personal property limits once open, matters more here than in a legacy downtown market.
North Dakota workers' comp only has one seller, and that changes how you shop for it
Every North Dakota employer must carry workers' comp from the first employee, but the policy can only come from Workforce Safety & Insurance, the state fund; private insurers aren't permitted to write it here at all. A West Fargo restaurant's WSI premium isn't something Insurance Kitchen shops across carriers the way we do with liability or property, but we still help new owners confirm proper classification and understand what WSI requires before their first hire's first shift.
A West Fargo restaurant opens in a brand-new Sheyenne Street building and skips builder's risk coverage during the buildout, then a contractor's error causes a kitchen fire before opening day.
A closer look at how West Fargo's documented risk factors actually play out.
A West Fargo restaurant opens in a brand-new Sheyenne Street building and skips builder's risk coverage during the buildout, then a contractor's error causes a kitchen fire before opening day.
- The setup: A first-time West Fargo owner assumes their future commercial property policy already covers the buildout phase, since the lease is signed and the space is technically theirs.
- The direct impact: Standard commercial property coverage typically doesn't start protecting a space mid-construction, and without a separate builder's risk policy, fire damage during buildout falls back on the owner or the contractor's own coverage, which may not fully match the loss.
- The coverage question: Confirm whether your buildout is covered under a dedicated builder's risk policy, not just your future commercial property policy's effective date.
- The fix: Binding builder's risk coverage the day construction starts, not the day the restaurant opens, is what actually protects a West Fargo owner through the buildout phase that defines so much of this city's growth.
This is exactly why West Fargo-specific coverage matters. A generic answer of "your commercial property policy covers the building" misses that new construction has its own coverage gap most legacy-downtown cities don't create as often.
Frequently asked questions
How much does restaurant insurance cost in West Fargo?
A comprehensive restaurant insurance package in West Fargo typically runs $1,800 to $6,600 per year for most single-unit operators, with full-bar, high-volume restaurants running $6,600 to $11,400 or more. General liability runs roughly $504 to $1,440 per year; a bundled BOP runs $1,560 to $1,800 per year; liquor liability runs $456 to $960 per year. North Dakota's rates generally track about 15% below the national average, with West Fargo's rapid growth keeping local demand for coverage rising.
Is workers' compensation required for a small West Fargo restaurant?
Yes, from your very first employee, whether full time, part time, seasonal, or occasional. North Dakota is a monopolistic workers' comp state, so coverage can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier. Skipping it exposes a West Fargo restaurant to the full cost of any claim plus a real penalty of up to $10,000.
Does a new West Fargo restaurant need builder's risk insurance?
Very likely, yes, and it's a common gap in a city this new. West Fargo's growth has come almost entirely through new construction along corridors like Sheyenne Street, and a standard commercial property policy typically doesn't cover a space during the buildout phase before it opens. A separate builder's risk policy, active from the day construction starts rather than the day the restaurant opens, closes that gap.
Can a West Fargo restaurant be sued for over-serving a customer?
Yes. N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee, or even a social host, who knowingly served that person, a minor, or an incompetent individual, with a six-year statute of limitations. Standalone liquor liability coverage, separate from general liability, is essential for any West Fargo restaurant opening with alcohol service.
What kind of insurance does a West Fargo restaurant actually need?
The core package is general liability, commercial property, and liquor liability if you serve alcohol, often bundled into a Business Owner's Policy for savings, plus builder's risk coverage during any new buildout given how much of West Fargo's restaurant space is newly constructed. Workers' compensation is legally required from your very first employee and has to be purchased directly through North Dakota's state fund, WSI.
Get West Fargo restaurant coverage built around your actual neighborhood and real local risk.
Tell us your concept and your West Fargo neighborhood. We'll put together the coverage that actually applies.
Get Your Free Quote →