



Restaurant Insurance in Bismarck, North Dakota
If you're a Bismarck restaurant owner searching for insurance that actually understands a state capital economy built around steady government employment rather than tourism swings, a 43-hour blizzard that remains the region's severe-weather benchmark, and a workers' comp system with only one approved seller, Insurance Kitchen builds coverage around that reality. The North Dakota State Capitol, the tallest building in the state at 242 feet, anchors Bismarck's downtown restaurant corridor. We build Bismarck restaurant coverage around your actual neighborhood and real local risk.
We know Bismarck's restaurant scene block by block
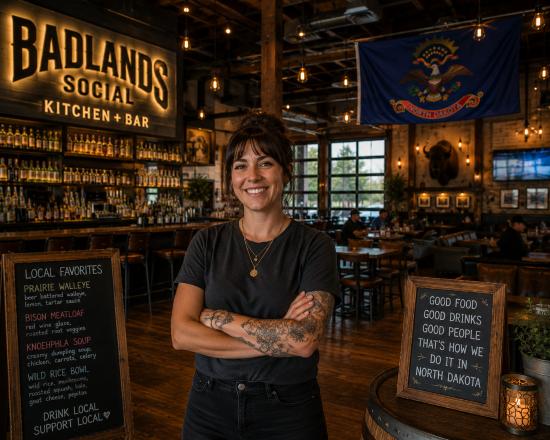
Bismarck's restaurant scene runs from a downtown built around the state's tallest building to a riverfront corridor along the Missouri that draws a steadier, less seasonal crowd than most cities this project has built. Here's what we watch for across its neighborhoods.
Downtown / 4th Street
Restaurants within walking distance of the North Dakota State Capitol and the state office complex see a genuinely reliable weekday lunch base built on state employment, a steadier revenue pattern than a tourism-driven district, though it also means traffic concentrates heavily on business days rather than spreading across the week.
Riverside / Sertoma Park area
Restaurants along Bismarck's Missouri River side benefit from real seasonal foot traffic from riverfront trails and events with sister city Mandan just across the water, and the river's flow here is regulated by upstream dam infrastructure, a materially different flood picture than the Red River Valley cities this project has also built in North Dakota.
Core coverage lines every Bismarck restaurant should evaluate
Restaurant insurance in Bismarck is a tailored bundle built around North Dakota law, local licensing, and your lease. Here's what actually protects Bismarck food service businesses.
General Liability Insurance
Protects against third-party bodily injury and property damage claims. Responds when guests slip, suffer foodborne illness, or get injured during delivery. Most landlords require $1M/$2M before lease signing.
Commercial Property Insurance
Covers your kitchen equipment, refrigeration and HVAC, tenant improvements, inventory, and business personal property against fire, equipment breakdown, and theft.
Business Owner's Policy (BOP)
Bundles general liability, commercial property, and business interruption into one package. Works best for single-unit restaurants with annual revenue under $3 million.
Liquor Liability Insurance
North Dakota has real civil dram shop liability: N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee or social host who knowingly furnished alcohol to that person, a minor, or an incompetent individual, with a six-year statute of limitations. Knowingly serving a prohibited person is also a class A misdemeanor under section 5-01-09. Standalone liquor liability coverage is essential, not optional, for any North Dakota establishment that serves alcohol.
Workers' Compensation Insurance
North Dakota is a monopolistic workers' comp state: coverage is mandatory from your first employee, full time, part time, seasonal, or occasional, but it can only be purchased through the state fund, Workforce Safety & Insurance (WSI); no private carrier is allowed to sell it here. Operating uninsured exposes an employer to the full cost of any claim plus a real penalty of up to $10,000, and it is illegal to deduct any part of the premium from an employee's wages.
Business Interruption Insurance
Replaces lost income and covers ongoing expenses when covered events force shutdowns or reduced capacity. Limits should reflect 3 to 6 months of net income plus fixed expenses.
What restaurant insurance typically costs in Bismarck
A rough range based on real North Dakota market data. Not a quote, just a starting point before you talk to an agent about your specific Bismarck location.
| Coverage | Typical Range | Why |
|---|---|---|
| General Liability Insurance | $480-$1,380/yr | North Dakota rates generally track about 15% below the national average, and Bismarck's status as a mid-sized capital city keeps premiums closer to the statewide baseline than Fargo's higher-density market. |
| Liquor Liability Insurance | $456-$960/yr | North Dakota has real civil dram shop liability under N.D. Cent. Code section 5-01-06.1, with a six-year statute of limitations that reaches social hosts as well as licensees, making standalone liquor liability coverage a genuine necessity for any Bismarck restaurant serving alcohol. |
| Commercial Property w/ Severe Winter Review | $792-$1,140/yr | Bismarck's documented 43-hour blizzard benchmark from March 1966 and the region's regular severe winter storms are real, cited reasons to confirm your policy's snow-load and roof-collapse coverage before the next season, not after a storm hits. |
| Workers' Compensation (WSI, mandatory from your first hire) | $576-$1,860/yr | North Dakota workers' comp can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier, and it's mandatory from a Bismarck restaurant's very first employee. Operating uninsured risks the full cost of any claim plus a real penalty of up to $10,000. |
| Business Owner's Policy (BOP), Bundled | $1,500-$1,740/yr | Bundles general liability and commercial property at a discounted rate, the standard starting point for most single-unit Bismarck cafes and downtown lunch spots. |
| Full-Service, High-Volume, Bundled | $6,600-$11,400/yr | Downtown full-bar restaurants with 15+ staff should budget toward this range; a comprehensive Bismarck package typically runs $1,740-$6,600/yr overall depending on alcohol service and payroll. |
Why Bismarck's government-anchored economy and North Dakota's single-source workers' comp system change what your policy needs to do
Bismarck restaurant coverage has to account for a steadier, less seasonal downtown customer base than most cities this project has built, layered against a state workers' comp system that only has one approved seller no matter which restaurant you own.
The March 1966 blizzard set Bismarck's severe-weather benchmark
The National Weather Service's own Bismarck office has documented that the blizzard of March 2 through 4, 1966, brought 43 consecutive hours of blizzard conditions to the city, one of the longest such stretches in North Dakota's recorded history, with 20 to 30 inches of snow and drifts as high as 40 feet across the region. Any Bismarck restaurant owner should treat that storm as the real local baseline for roof-load and business-interruption planning when reviewing a property policy, rather than defaulting to a generic statewide winter-weather estimate.
North Dakota workers' comp only has one seller, and that changes how you shop for it
Every North Dakota employer must carry workers' comp from the first employee, but the policy can only come from Workforce Safety & Insurance, the state fund; private insurers aren't permitted to write it here at all. A Bismarck restaurant's WSI premium isn't something Insurance Kitchen shops across carriers the way we do with liability or property, but we still help owners confirm they're classified correctly and understand what WSI requires before their first hire's first shift.
A Bismarck restaurant assumes its downtown government-district lease already includes adequate liquor liability coverage, and a server is sued after over-serving a customer.
A closer look at how Bismarck's documented risk factors actually play out.
A Bismarck restaurant assumes its downtown government-district lease already includes adequate liquor liability coverage, and a server is sued after over-serving a customer.
- The setup: A downtown Bismarck restaurant owner assumes a standard general liability policy already covers alcohol-related incidents, since the lease requires "liability insurance" without specifying the type.
- The direct impact: General liability policies broadly exclude liquor-related claims, and the injured party's attorney files directly under N.D. Cent. Code section 5-01-06.1, which reaches any licensee who knowingly over-served a visibly intoxicated patron.
- The coverage question: Confirm whether your policy actually includes a standalone liquor liability endorsement, not just a generic general liability limit, before your next lease renewal.
- The fix: Carrying dedicated liquor liability coverage, distinct from general liability, is what actually closes this gap for any Bismarck restaurant serving alcohol.
This is exactly why Bismarck-specific coverage matters. A generic answer of "my liability policy covers that" misses that North Dakota's dram shop exposure requires its own dedicated coverage line.
Frequently asked questions
How much does restaurant insurance cost in Bismarck?
A comprehensive restaurant insurance package in Bismarck typically runs $1,740 to $6,600 per year for most single-unit operators, with full-bar, high-volume restaurants running $6,600 to $11,400 or more. General liability runs roughly $480 to $1,380 per year; a bundled BOP runs $1,500 to $1,740 per year; liquor liability runs $456 to $960 per year. North Dakota's rates generally track about 15% below the national average, and Bismarck's mid-sized capital-city market keeps premiums closer to the statewide baseline than Fargo's denser corridor.
Is workers' compensation required for a small Bismarck restaurant?
Yes, from your very first employee, whether full time, part time, seasonal, or occasional. North Dakota is a monopolistic workers' comp state, so coverage can only be purchased through the state fund, Workforce Safety & Insurance, not a private carrier. Skipping it exposes a Bismarck restaurant to the full cost of any claim plus a real penalty of up to $10,000, and employers can't legally deduct any part of the premium from a worker's paycheck.
Can a Bismarck restaurant be sued for over-serving a customer?
Yes. N.D. Cent. Code section 5-01-06.1 lets anyone injured by an obviously intoxicated person sue a licensee, or even a social host, who knowingly served that person, a minor, or an incompetent individual, with a six-year statute of limitations. Serving a prohibited person is also a class A misdemeanor that can jeopardize a liquor license. Standalone liquor liability coverage, separate from general liability, is essential for any Bismarck restaurant serving alcohol.
Does Bismarck's winter weather affect restaurant insurance costs?
Yes, in a documented way. Bismarck's own National Weather Service office has recorded 43 consecutive hours of blizzard conditions during the March 1966 storm, one of the region's defining severe-weather events, and the city still sees regular heavy snow and extreme cold most winters. Restaurant owners should confirm their commercial property policy's snow-load, roof-collapse, and frozen-pipe coverage reflects that real regional risk.
What kind of insurance does a Bismarck restaurant actually need?
The core package is general liability, commercial property, and liquor liability if you serve alcohol, often bundled into a Business Owner's Policy for savings. Workers' compensation is legally required from your very first employee and has to be purchased directly through North Dakota's state fund, WSI, rather than shopped across private carriers the way the rest of your coverage can be.
Get Bismarck restaurant coverage built around your actual neighborhood and real local risk.
Tell us your concept and your Bismarck neighborhood. We'll put together the coverage that actually applies.
Get Your Free Quote →