




Restaurant Insurance in Taos, New Mexico
If you're a Taos restaurant owner searching for insurance that actually understands a wildfire currently burning in the national forest just outside town, a state with no cap at all on liquor liability damages after the courts struck it down, and a UNESCO World Heritage Site that's been continuously inhabited for roughly 1,000 years, Insurance Kitchen builds coverage around that reality. The Frijoles Fire has burned more than 15,000 acres and sent smoke directly into the Taos Valley. We build Taos restaurant coverage around your actual neighborhood and local risk.
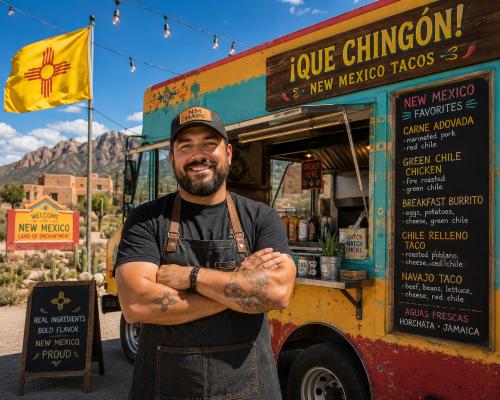
We know Taos's restaurant scene block by block
Taos's restaurant scene sits around a 1796 colonial plaza next to one of the oldest continuously inhabited communities in the country, with real wildfire and windstorm risk to plan around. Here's what we watch for across its neighborhoods.
Taos Downtown Historic District
Listed on the National Register of Historic Places on July 8, 1982, and the New Mexico State Register of Cultural Properties the same year. Thirty acres centered on Taos Plaza, part of the original 1796 Don Fernando de Taos land grant, today home to the Taos Inn and the dense restaurant and gallery core of downtown.
Taos Pueblo
Designated a UNESCO World Heritage Site in 1992 and a National Historic Landmark on October 9, 1960. A living Native American community continuously inhabited for roughly 1,000 years, one of the oldest inhabited structures in the country.
Core coverage lines every Taos restaurant should evaluate
Restaurant insurance in Taos is a tailored bundle built around New Mexico law, local licensing, and your lease. Here's what actually protects Taos food service businesses.
General Liability Insurance
Protects against third-party bodily injury and property damage claims. Responds when guests slip, suffer foodborne illness, or get injured during delivery. Most landlords require $1M/$2M before lease signing.
Commercial Property Insurance
Covers your kitchen equipment, refrigeration and HVAC, tenant improvements, inventory, and business personal property against fire, equipment breakdown, and theft.
Business Owner's Policy (BOP)
Bundles general liability, commercial property, and business interruption into one package. Works best for single-unit restaurants with annual revenue under $3 million.
Liquor Liability Insurance
NMSA 1978 § 41-11-1 holds a licensee liable for serving a patron who was actually intoxicated, visibly so, and known to be intoxicated by the server, with no damage cap at all after the New Mexico Supreme Court struck down the statutory cap as unconstitutional in Richardson v. Carnegie Library Restaurant (1988).
Workers' Compensation Insurance
Covers medical expenses and lost wages for work-related injuries. NMSA 1978 § 52-1-2 requires coverage once you employ 3 or more workers, counting family members and part-timers, and once you've hit that threshold, temporarily dropping below it doesn't remove the requirement.
Business Interruption Insurance
Replaces lost income and covers ongoing expenses when covered events force shutdowns or reduced capacity. Limits should reflect 3 to 6 months of net income plus fixed expenses.
What restaurant insurance typically costs in Taos
A rough range based on real New Mexico market data. Not a quote, just a starting point before you talk to an agent about your specific Taos location.
| Coverage | Typical Range | Why |
|---|---|---|
| General Liability Insurance | $550–$2,600/yr | Scales with your landlord's required limits and your building's age, especially around the historic Plaza district. |
| Liquor Liability Insurance | $400–$2,200/yr | New Mexico has no cap at all on liquor liability damages after the state Supreme Court struck the statutory cap down, and most Taos leases and lenders require this coverage regardless. |
| Commercial Property w/ Wildfire Endorsement | $1,800–$5,800/yr | The active Frijoles Fire has burned over 15,000 acres in the Santa Fe National Forest and sent smoke directly into the Taos Valley, a current, ongoing reminder that wildfire risk here is real, not theoretical. |
| Workers' Compensation | $0.35–$1.60 per $100 of payroll | Once you're staffing three or more people in New Mexico, family and part-time hires included, coverage becomes required. |
| Business Owner's Policy (BOP), Bundled | $1,400–$4,200/yr | Bundles general liability and commercial property at a discounted rate, the standard starting point for most single-unit Taos restaurants. |
| Full-Service Resort, Bundled | $4,800–$12,000/yr | Restaurants running a full bar during peak ski or summer art-tourism season should budget toward the higher end. |
Why the Frijoles Fire and New Mexico's uncapped liquor liability law change what your policy needs to do
Taos restaurant coverage has to account for an active, current wildfire burning near the city, plus a documented severe windstorm, on top of New Mexico's liquor liability framework, which carries real exposure precisely because the courts removed the damage ceiling.
An active wildfire and a documented windstorm both show real, recent risk here
The Frijoles Fire started from a lightning strike on August 4, 2026 in the Santa Fe National Forest west of Taos and had burned more than 15,000 acres as of late August, sending smoke directly into the Taos Valley and prompting air-quality warnings. Separately, a windstorm on December 15, 2021 produced peak winds of 103 mph in Taos Ski Valley, damaging at least a dozen homes and businesses in nearby El Prado and prompting both a Taos County emergency declaration and a state emergency declaration. Two different disaster types, both documented and both close to town, are why a Taos restaurant's coverage needs to account for wildfire and severe wind specifically.
New Mexico's liquor liability law carries real exposure precisely because it has no cap
NMSA 1978 § 41-11-1 holds a licensee liable when a patron was actually intoxicated, visibly so, and known to be intoxicated by the server. The New Mexico Supreme Court struck down the statute's original damage cap as unconstitutional in Richardson v. Carnegie Library Restaurant (1988), meaning there's no dollar ceiling on liability. For a resort town where alcohol service is a meaningful part of the business during ski and summer art-tourism season, understanding this uncapped framework matters.
Dry, windy conditions raise wildfire risk in the Santa Fe National Forest near your Taos restaurant.
A closer look at how Taos's documented risk factors actually play out.
Dry, windy conditions raise wildfire risk in the Santa Fe National Forest near your Taos restaurant.
- The current situation: The Frijoles Fire, sparked by lightning in August 2026, has burned more than 15,000 acres and is still sending smoke into the Taos Valley.
- The wind risk: A December 2021 windstorm produced 103 mph winds in Taos Ski Valley and damaged a dozen homes and businesses in nearby El Prado, a documented benchmark for severe wind in this area.
- The building-age question: If your restaurant occupies a historic building near the Plaza, confirm your property policy's replacement-cost basis matches the building's actual age and construction.
- The fix: A commercial property policy with confirmed wildfire and wind coverage, checked against events this severe, is what actually responds to a loss.
This is exactly why Taos-specific coverage matters. A generic statewide policy doesn't automatically account for wildfire and windstorm risk documented this recently and this severely.
Frequently asked questions
How much does restaurant insurance cost in Taos?
Restaurant insurance in Taos typically runs $3,500 to $12,000 per year for a standard package combining general liability, commercial property, and workers' compensation. General liability runs $550 to $2,600 per year; commercial property with a wildfire endorsement runs $1,800 to $5,800 per year; workers' compensation runs roughly $0.35 to $1.60 per $100 of payroll. Liquor liability runs $400 to $2,200 per year.
Can a Taos restaurant be held liable for over-serving a customer, and is there a damage limit?
Yes, and no, there's no cap. NMSA 1978 § 41-11-1 holds a licensee liable for serving a patron who was actually intoxicated, visibly so, and known to be intoxicated by the server. The New Mexico Supreme Court struck down the statute's original damage cap as unconstitutional in Richardson v. Carnegie Library Restaurant (1988), so liability here is genuinely open-ended.
Is wildfire currently affecting Taos, and does that change insurance needs?
Yes. The Frijoles Fire, sparked by lightning in August 2026, has burned more than 15,000 acres in the nearby Santa Fe National Forest and has sent smoke directly into the Taos Valley. Confirm your commercial property policy includes wildfire coverage and that your business interruption coverage responds to smoke-driven closures, not just direct fire damage.
Does Taos Pueblo's UNESCO status affect the local restaurant economy?
Indirectly, yes. Taos Pueblo has been continuously inhabited for roughly 1,000 years and was designated a UNESCO World Heritage Site in 1992, drawing real, documented tourism traffic into Taos alongside the town's ski and art-colony draws. That kind of steady visitor demand is worth factoring into staffing and general liability planning.
Is workers' compensation required for a small Taos restaurant with only a few employees?
New Mexico ties the requirement to headcount, not business size in general. NMSA 1978 § 52-1-2 kicks in at three employees, counting family members and part-time or seasonal staff, and established case law says the obligation sticks even if you later dip back under that number.
Get Taos restaurant coverage built around your actual neighborhood and real local risk.
Tell us your concept and your Taos neighborhood. We'll put together the coverage that actually applies.
Get Your Free Quote →